- October 4, 2026
- Posted by: admin
- Category: BitCoin, Blockchain, Cryptocurrency, Investments
Coin Metrics has rebuilt Ethereum’s historical Standard Flow Metrics, raising a timing problem for tests that treat exchange outflows as a trading signal.
The crypto data provider’s Oct. 1 notice says it recomputed Ethereum Standard Flow Metrics from the network’s first block using its most up-to-date information as part of its Ethereum Point-in-Time release. The affected scope is all ETH Flow Metrics at daily and hourly frequencies, with corrected history available for backfilling.
That creates a practical distinction for investment research. A chart downloaded today can describe past flows using knowledge acquired later. A backtest, which replays a trading rule through historical data, needs the information available when each decision would have occurred. Those are different information sets, even when their observations carry the same dates.
The notice supplies no revision amounts or ETH strategy comparison. The immediate consequence is a need to identify data vintage, meaning the version of the data used in the test; any effect on returns still requires measurement.
Why the same historical date can tell a different story
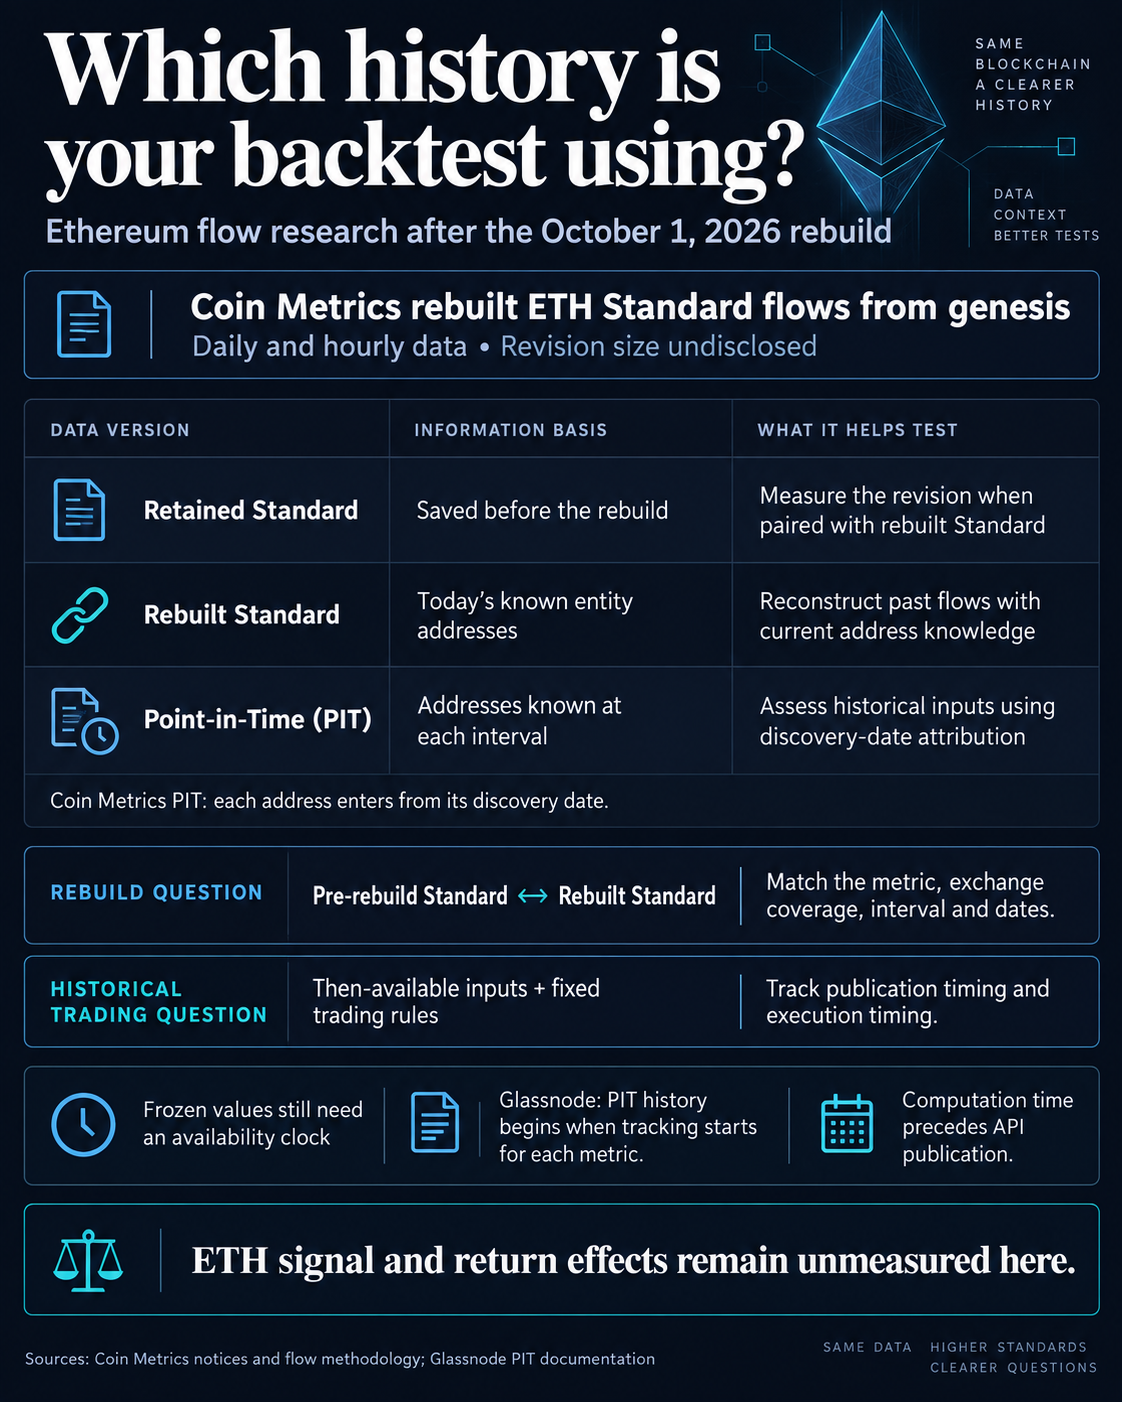
Coin Metrics’ flow methodology makes the distinction concrete. Standard metrics use all addresses currently known to belong to an exchange or other tracked entity, with each address’s history starting at its first nonzero balance. Past values can be restated when additional entity addresses are identified.
Its Point-in-Time, or PIT, series instead uses addresses known to belong to the entity during the historical interval. An address contributes from its discovery date, and later discoveries do not rewrite earlier PIT intervals. The provider documents daily and hourly PIT counterparts to Standard exchange-flow metrics.
The underlying issue is attribution. A transfer can be assigned to an exchange retrospectively once the provider identifies the wallet. That fuller reconstruction may be useful for analyzing past supply movements with today’s address coverage. Establishing what a trader could have recognized requires the address information and values available at that earlier moment.
Coin Metrics had outlined the recomputation on Sept. 28 to maintain that distinction, expecting ETH completion on Sept. 30. Its completion notice was posted Oct. 1 at 17:04 UTC; notice timing alone does not date every affected value’s availability.
Two comparisons must also stay separate. Standard versus PIT tests different address-knowledge rules. Retained Standard history from before and after the rebuild is the comparison needed to measure this particular revision. PIT is a distinct attribution method. A copy of pre-rebuild Standard values preserves a particular version of the Standard product.
CryptoQuant’s ETH Exchange Flows documentation explicitly warns that the endpoint does not support PIT accuracy. It says historical values may change as exchange wallets are discovered, added and validated through periodic clustering updates.
CryptoQuant schedules automatic updates for Tuesday at 00:00 UTC each week and says values can change slightly, especially recent observations. Each provider’s revisions require their own measurements and update records.
For an analyst, retaining an old query date is therefore insufficient if the historical values are fetched again from a mutable endpoint. The dates of the observations may remain the same while the information used to construct them changes.
The interpretation of an outflow also needs restraint. A withdrawal measures movement relative to attributed exchange wallets. A claim about buying or profitable trading requires additional evidence.
Glassnode’s BTC illustration isolates data-vintage risk
Glassnode supplied an illustration of the problem in a March 13, 2026, hypothetical backtest. It used Binance’s BTC exchange balance to enter the market when a five-day moving average fell below a 14-day average and exit when the shorter average rose above the longer one.
The test covered Jan. 1, 2024, through March 9, 2026, starting with $1,000 and charging 0.1% per trade. Glassnode said it repeated the test using PIT balances while keeping the signal logic, parameters, dates and fees unchanged. The provider reported worse performance with PIT data than with revised balances.
The useful comparison is that the rule stayed fixed while the data variant changed. A historical balance pattern reconstructed with later knowledge can trigger different decisions from a pattern built from contemporaneous knowledge.
Glassnode supplied this BTC balance result, and the test remains unreplicated in this analysis. Its relevance to ETH is the measurement approach: hold the rule fixed and compare the data vintages. ETH signal and return effects require their own experiment.
The availability clock adds a further constraint. Glassnode’s PIT documentation adds two limits to the shorthand promise of replaying the past.
First, PIT history exists only from the date tracking began for each metric. Before July 2025, coverage was limited to BTC, ETH and selected tokens and metrics; tracking expanded across all platform metrics from July 2025. A metric added then does not acquire earlier PIT observations merely because regular historical data exists.
Second, the timestamp attached to an observation is not necessarily when a trader could retrieve it. Glassnode says it has recorded relevant computed_at timestamps since September 2024, omitting the field when unavailable, and that API publication follows computation with a delay.
An unchanged historical value addresses later revision. Replaying a trading decision also requires placing the input after its actual publication. A test that acts before the input could be accessed still uses information from the future.
For Coin Metrics’ ETH series, that means documenting each metric’s first tracking date and historical customer availability. Glassnode’s coverage dates and publication disclosures apply to its own products.
The evidence needed to measure an ETH trading effect
Measuring this rebuild requires paired observations from the same provider and metric, with matching exchange coverage, intervals and dates. For the revision question, that means retained pre-rebuild Standard values alongside the post-rebuild Standard history. For the trading question, it also means an information set demonstrably available at each decision time.
The rule must remain fixed across the comparison: the same entry and exit conditions, parameters and evaluation window. Availability cutoffs and execution timing belong in the test, alongside trading costs. Otherwise, changing the strategy while changing the data would leave the source of any performance difference unclear.
The comparison should then distinguish changed input values from changed signals, changed trades and changed returns. A revision can matter to the dataset without changing a particular rule’s decisions.
The decisive follow-up is a paired ETH dataset and a fixed-rule replay that separates data changes from trading changes. Revised history can describe supply with today’s address knowledge. A claim that outflows offered a usable trading edge requires reproducible inputs, publication timing and trading decisions.
The post Ethereum’s past outflow charts can change when more exchange wallets are identified appeared first on CryptoSlate.